Financial planning tools help individuals manage their money, but not all tools serve the same purpose. Personal Capital and Mint are two popular options, each catering to different user needs. Personal Capital is geared toward users seeking detailed investment insights and wealth management, while Mint emphasizes budgeting and expense monitoring for daily financial oversight. Understanding these differences clarifies which tool aligns with your financial priorities and usage patterns. Choose Personal Capital if you want a comprehensive view of your investments and net worth, especially if you’re planning for retirement or building wealth. Opt for Mint if you prefer simple, user-friendly budgeting and expense alerts to keep track of daily spending. This comparison highlights the key features, strengths, and limitations to help you make an informed decision based on your financial management style.
Get ready for Prime Big Deal Days — try Prime free
Exclusive member deals on October 6–7, plus fast free delivery. Cancel anytime.
Start your free trialAs an affiliate, we earn on qualifying purchases.
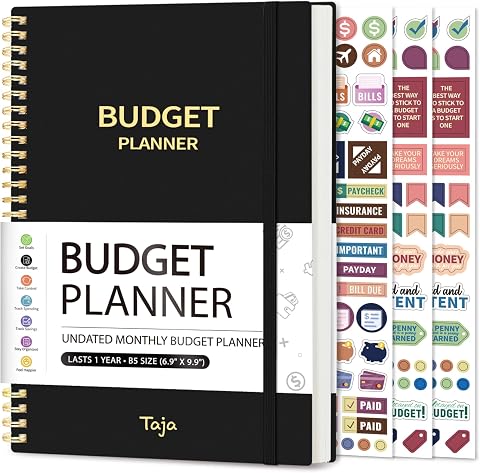
Taja Budget Planner, Undated Budget Book with Expense Tracker, 6.9" x 9.9"
- ✔ Brand: Taja
- ✔ Target Audience: Adult
- ✔ Item Count: 1
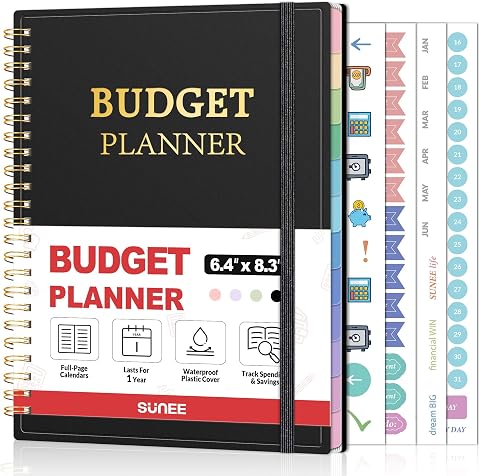
SUNEE Budget Planner – Monthly Budget Book with Expense Tracker, Undated 12-Month Finance Organizer, A5 (6.4" x 8.3")
- ✔ Size: A5 (6.4" x 8.3")
- ✔ Pages: Approximately 120
- ✔ Cover Material: Water-resistant

Budget Planner – Monthly Budget Book with Expense Tracker, 5.8" x 8.2"
- ✔ Size: 5.8" x 8.2"
- ✔ Duration: 14 months
- ✔ Cover: Pink with gold accents
At a Glance
| Criteria | Personal Capital | Mint | Winner |
|---|---|---|---|
| Ease of Use | Moderate complexity, user-friendly interface with investment dashboards | Very easy, simple interface designed for quick setup | A |
| Investment Management | Advanced investment tools, portfolio analysis, retirement planning | Basic investment tracking, no advisory services | B |
| Budgeting Features | Limited budgeting, more focus on investments | Robust budgeting, expense tracking, alerts | B |
| Fee Structure | Free with optional paid advisory services | Free with ads, optional premium plans | A |
| Security & Privacy | High security, bank-level encryption | Secure with encryption, data privacy policies | A |
| Reporting & Analytics | In-depth investment reports, net worth tracking | Standard reports, basic expense summaries | A |
| Customer Support | Premium support with financial advisor access | Standard customer support via chat and email | B |
| Integration Capabilities | Connects with various investment accounts, wealth management integrations | Integrates with bank accounts, credit cards, and bills | B |
Taja Budget Planner, Undated Budget Book with Expense Tracker, 6.9" x 9.9"
<p>The <strong>Taja Budget Planner</strong> stands out for its undated format, offering maximum flexibility for users who prefer to start or pause their budgeting at any time. Its straightforward layout makes tracking income, expenses, and savings accessible for adults, while the bonus stickers and comprehensive guide add a touch of personalization and educational value. Compared with the <strong>SUNEE Planner</strong>, it lacks a dedicated 12-month structure but excels in adaptability. However, its basic design may not satisfy those seeking advanced financial tools or a more modern aesthetic.</p>
Pros:
- Undated format allows flexible planning anytime
- Includes bonus stickers for personalization
- Comprehensive guidebook offers budgeting tips
- Durable with elastic band and extra storage pocket
Cons:
- No pre-printed dates, requiring manual entry
- Limited to adult users; may not appeal to younger audiences
- Design may be too basic for advanced users
Best for: Budgeters who want a flexible, no-frills planner to tailor to their schedule.
Not ideal for: Users seeking digital integration or highly detailed financial analysis.
Bottom line: A versatile, easy-to-use planner ideal for flexible budgeting and beginners.
“A versatile, easy-to-use planner ideal for flexible budgeting and beginners.”
SUNEE Budget Planner – Monthly Budget Book with Expense Tracker, Undated 12-Month Finance Organizer, A5 (6.4" x 8.3")
<p>The <strong>SUNEE Budget Planner</strong> is designed for those who want a vibrant, organized approach to annual financial management. Its full-page monthly calendars, colorful tabs, and sections for debt and savings make navigating your finances engaging and straightforward. Compared to the <strong>Budget Planner with Gold Accents</strong>, it offers a more comprehensive monthly structure, but it doesn’t include digital features or refill options. Its water-resistant cover and included accessories boost longevity, yet some users may find its colorful, busy design less minimalist than others.</p>
Pros:
- Undated design allows start at any time
- Colorful tabs and pages improve visibility
- Durable water-resistant cover and elastic band
- Includes sections for debt, savings, and bill tracking
Cons:
- Lacks digital integration or app support
- Limited to a single year without refill options
- Design may be too busy for minimalists
Best for: Individuals seeking a durable, colorful planner with clear monthly organization for the full year.
Not ideal for: Those preferring a sleek, minimalist aesthetic or digital tracking options.
Bottom line: A vibrant, durable choice for year-long financial tracking with excellent organizational features.
“A vibrant, durable choice for year-long financial tracking with excellent organizational features.”
Budget Planner – Monthly Budget Book with Expense Tracker, 5.8" x 8.2"
<p>The <strong>Budget Planner with Gold Accents</strong> offers a sleek, stylish option for long-term financial planning. Covering 14 months, its elegant pink with gold details makes budgeting feel special. Its layout is straightforward, focusing on monthly pages and expense tracking, making it perfect for users who prefer a minimalistic approach. Compared with the <strong>Taja Planner</strong>, it’s less flexible due to fixed duration, but it compensates with a more refined aesthetic. Its basic features might not satisfy those needing advanced tools or digital options.</p>
Pros:
- Long 14-month coverage supports extended planning
- Stylish design with gold accents
- Compact size fits easily into bags
- Durable coil binding ensures longevity
Cons:
- Limited to basic budgeting features
- Lacks digital or app-based tools
- Design may not appeal to minimalists
Best for: Style-conscious users seeking a long-term, elegant budgeting companion.
Not ideal for: Those who want extensive financial features or digital connectivity.
Bottom line: A chic, long-term planner suited for those prioritizing style and extended planning without complex features.
“A chic, long-term planner suited for those prioritizing style and extended planning without complex features.”
As an Amazon Associate we earn from qualifying purchases.
Key Differences
The core distinction between Personal Capital and Mint lies in their primary focus areas. Personal Capital excels in wealth management, offering tools for investment tracking, portfolio analysis, and retirement planning, making it ideal for users with significant assets or those planning for long-term wealth growth. Mint, on the other hand, prioritizes daily financial management, providing comprehensive budgeting, expense tracking, and bill reminders, which appeals to individuals seeking straightforward control over their everyday finances. In practice, this means Personal Capital is better suited for users with complex investment portfolios or those nearing retirement, whereas Mint suits users who want easy-to-use tools for managing cash flow and expenses. The tradeoff is that Personal Capital’s advanced features come with a steeper learning curve and potentially higher costs if opting for advisory services, whereas Mint’s simplicity might limit detailed investment insights but offers more immediate expense oversight.
Detailed Comparison
Ease of Use (Mint wins — moderate)
Mint scores higher on ease of use, with a straightforward interface designed for quick setup and daily expense management. It’s ideal for users who want minimal fuss and instant expense tracking. Personal Capital, while user-friendly, involves more steps to input investment data and analyze portfolios, making it slightly more complex but more powerful for wealth management. The difference is moderate; if you prefer simplicity, Mint is preferable. For those comfortable with financial details and wanting deeper insights, Personal Capital’s interface is manageable but requires a learning curve.
Investment Management (Personal Capital wins — major)
Personal Capital outperforms Mint significantly here, offering detailed portfolio analysis, retirement planning tools, and personalized investment advice. It connects to various investment accounts and provides in-depth insights into asset allocation and risk. Mint provides basic investment tracking without advanced analysis, making it suitable for users who want a simple view of their investments but not detailed management. This difference is major; if investment tracking and planning are priorities, Personal Capital is the clear choice. If investments are secondary to everyday budgeting, Mint’s limited features suffice.
Budgeting Features (Mint wins — major)
Mint excels in budgeting with real-time expense tracking, customizable budgets, alerts for overspending, and bill reminders. It provides a clear picture of cash flow, making it ideal for managing day-to-day finances. Personal Capital offers some budgeting tools but emphasizes wealth and investment tracking more. Therefore, Mint wins decisively for budgeting. The gap is major; if your primary goal is controlling expenses and staying within budgets, Mint is more effective.
Fee Structure (Mint wins — moderate)
Both tools are free to use, but Personal Capital charges for advisory services and wealth management if you opt for its premium features, which can be significant for high-net-worth users. Mint remains free with optional premium plans that add features like ad-free experience and extra insights. For users who want free basic budgeting, Mint is clearly more economical. For those seeking advanced investment advice and willing to pay for it, Personal Capital’s fees may be justified. The difference is moderate; consider your investment needs and willingness to pay for advisory services.
Security & Privacy (Personal Capital wins — minor)
Both platforms employ bank-level encryption and adhere to strict privacy policies. Personal Capital emphasizes secure connections to investment accounts and provides detailed privacy assurances, which is critical for wealth management. Mint also maintains high security standards but is more targeted toward consumer banking and budgeting data. Overall, they are comparable; the choice depends more on the trust you place in financial institutions handling your data.
Reporting & Analytics (Personal Capital wins — moderate)
Personal Capital offers extensive reporting and analytics, including net worth tracking, asset allocation, and retirement projections, making it suitable for strategic financial planning. Mint provides basic expense reports and budget summaries, which are sufficient for everyday financial oversight but lack depth. The gap is moderate; choose Personal Capital if you want detailed analytics for wealth growth, or Mint if you need quick, simple reports.
Customer Support (Personal Capital wins — moderate)
Personal Capital provides premium support, including access to financial advisors for clients using its wealth management services. Mint offers standard customer support via chat and email, with premium options mainly for additional features. For users seeking personalized financial advice, Personal Capital’s support is more comprehensive. The difference is moderate; for basic support needs, Mint suffices, but for professional guidance, Personal Capital is superior.
Integration Capabilities (Mint wins — moderate)
Both tools connect to a variety of financial accounts. Personal Capital integrates with investment accounts, retirement plans, and banks, emphasizing holistic wealth management. Mint connects with bank accounts, credit cards, loans, and bills for a comprehensive view of cash flow. For investment-centric users, Personal Capital’s integrations are more extensive; for everyday expense management, Mint’s integrations are sufficient. The difference is minor to moderate depending on your financial ecosystem.
Personal Capital: Pros and Cons
Pros:
- Deep investment analysis and retirement planning tools
- Holistic view of net worth and assets
- Premium financial advice available
- Secure and trusted platform for wealth management
Cons:
- More complex to learn and set up
- Potential costs for advisory services
- Less focused on daily expense management
Mint: Pros and Cons
Pros:
- Excellent for budgeting and daily expense tracking
- Very easy to use and quick to set up
- Free with optional premium features
- Strong integration with banking and bills
Cons:
- Limited investment analysis and planning
- Less suitable for wealth management
- Basic reports may miss detailed insights
Who Should Choose What
Choose Personal Capital if:
- You have significant investments and want detailed portfolio analysis
- Planning for retirement or wealth accumulation
- Willing to pay for personalized financial advice
- You prefer a comprehensive view of your finances, including assets and liabilities
Choose Mint if:
- Your primary need is simple budgeting and expense tracking
- You prefer an easy-to-use platform with quick setup
- Limited investment management needs
- You want a free tool to monitor daily financial activities
Value for Money
For users who prioritize investment management and wealth planning, paying extra for Personal Capital’s advanced features can be justified, especially if managing large portfolios or planning for retirement. For those focused on day-to-day financial control, Mint offers valuable tools at no cost, providing excellent value for budget-conscious users. The decision hinges on whether detailed investment insights are worth the additional complexity and potential expense, or if straightforward budgeting suffices for your financial goals.Final Verdict
Choose Personal Capital if you are a serious investor or planning for retirement and want detailed analytics and advisory support. Opt for Mint if you need a simple, effective tool for managing daily expenses and budgets without complexity or additional cost. The biggest deciding factor is your investment activity and wealth management needs versus your desire for ease and expense control. For most users, Personal Capital’s comprehensive features justify the higher learning curve and potential costs if wealth building is your focus, while Mint remains the best choice for straightforward budgeting.
Frequently Asked Questions
Can I use both Personal Capital and Mint together?
Yes, many users find value in combining the detailed investment management of Personal Capital with the budgeting strengths of Mint. Using both allows for a comprehensive view of finances, but be aware of managing multiple accounts and data privacy considerations.
Is Personal Capital suitable for small investors?
Yes, but its advanced features are most beneficial for users with sizable portfolios or planning for retirement. Small investors may find Mint sufficient for their needs and more straightforward to use.
Are there any hidden fees or costs?
Personal Capital offers free tools but charges for wealth management and advisory services. Mint is free with optional premium plans. Always review the service details before committing.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.