TL;DR

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
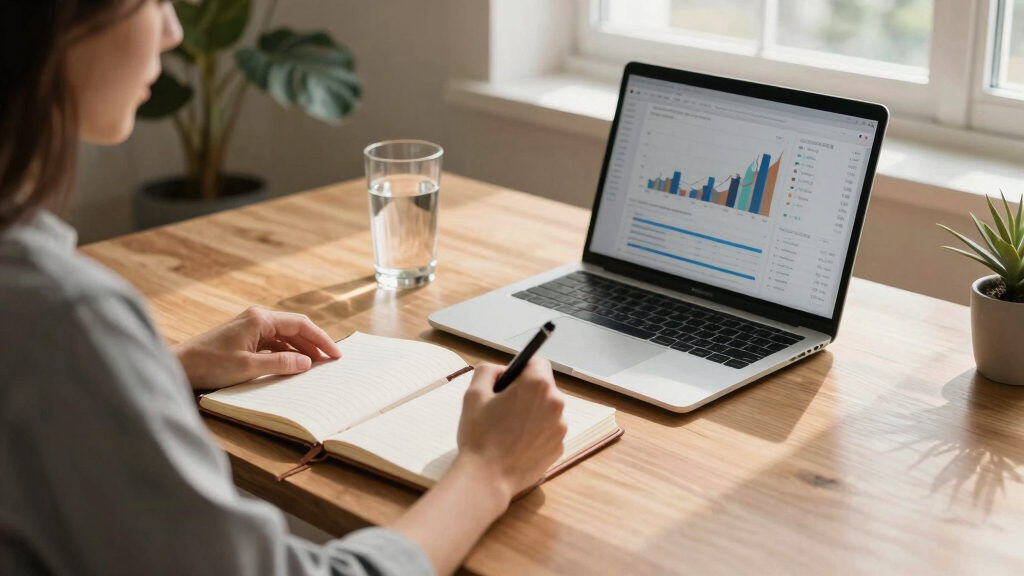
Financial planning notebooks are customized tools—physical or digital—that help you track income, expenses, and goals. Regular use boosts awareness and discipline, making you more confident in managing your money.
Imagine holding a notebook that’s your personal money map—colorful tabs, scribbled notes, and checkmarks. It’s more than just paper or pixels; it’s a mental anchor that makes your financial goals real.
Whether you’re trying to pay off debt, save for a house, or just get a grip on your spending, a well-designed financial planning notebook acts like a coach sitting right beside you. It’s about turning vague dreams into concrete steps—one entry at a time.
Choose a notebook style—physical or digital—that fits your personality to stay consistent.
Regular, honest updates turn a simple notebook into a powerful tool for financial awareness.
Visuals like charts and color coding make tracking progress intuitive and motivating.
Blending digital automation with physical journaling offers the best of both worlds.
Personalize your notebook to match your specific financial goals for better results.
What Makes a Financial Planning Notebook a Game-Changer?
Think of a financial planning notebook as your personal money gym. It’s where you lift the heavy weights of debt and stretch your savings muscles. These notebooks aren’t just for jotting numbers—they’re designed to boost your awareness and discipline.
For example, you might have a section where you record every coffee purchase—$4 here, $3 there—before you know it, you’ll realize how much that daily latte adds up over a month. That awareness sparks change.
Recent research shows that people who physically write down their goals are 42% more likely to achieve them. The act of writing makes your intentions stick, especially when it’s in your own handwriting or on a personalized template.
As an affiliate, we earn on qualifying purchases.
How to Pick the Perfect Financial Notebook for Your Style
Choosing the right notebook depends on your personality and goals. Do you love color and creativity? A vibrant, customizable journal might motivate you. Prefer digital? An app with interactive charts could be your best friend.
Here’s a simple step-by-step to find your match:
- Assess your tech comfort—are you more paper or screen person?
- Decide what features matter—budget sheets, goal trackers, or educational tips.
- Set a budget—some high-end planners cost $50+, while free PDFs or apps are just as effective.
- Test a few options—many sites offer free samples or trial versions.
- Stick with what motivates you most—consistency beats perfection.
For example, Sarah, a freelance artist, swears by her colorful, sticker-adorned notebook because it makes tracking her irregular income feel fun rather than tedious.
As an affiliate, we earn on qualifying purchases.
Comparison Table: Physical Notebooks vs. Digital Templates
| Feature | Physical Notebooks | Digital Templates |
|---|---|---|
| Accessibility | Can be accessed anytime, anywhere, no tech needed | Requires device and internet, but syncs across platforms |
| Customization | High—write, draw, decorate freely | High—editable, with charts and automation |
| Ease of Use | Simple, tactile, no learning curve | Requires initial setup, but quick updates |
| Environmental Impact | Reusable if kept in good shape | Electronic, depends on device use |
| Accountability | High—physical act of writing reinforces commitment | High—reminders and alerts boost consistency |
As an affiliate, we earn on qualifying purchases.
Top 5 Tips to Keep Your Financial Notebook Alive and Thriving
- Make it a daily habit: Spend 5 minutes every morning or evening updating your entries.
- Set clear goals: Write down what you want to achieve—pay off $5,000 debt, save $10K, etc.
- Use visuals: Add pie charts, bar graphs, or color codes to see progress at a glance.
- Reflect weekly: Review your entries, celebrate wins, and adjust plans.
- Be honest: Record every expense, even the small ones. Transparency fuels change.
For instance, Mark started tracking his grocery spending daily. After a month, he cut back by $150 because he saw how often he bought snacks he didn’t need.
As an affiliate, we earn on qualifying purchases.
Latest Trends: Digital Meets Classic in Money Journaling
Digital and interactive notebooks are reshaping how we manage money. They combine the tactile satisfaction of writing with tech-savvy features like automatic expense tracking, reminders, and visual dashboards.
For example, apps like YNAB or EveryDollar sync with your bank accounts, giving you real-time updates. Meanwhile, printable PDFs let you customize your pages at home, blending old-school planning with new tech.
Recent surveys reveal that 65% of Millennials and Gen Z prefer digital tools for financial planning, citing convenience and instant updates. The trend is clear: blending the physical and digital worlds keeps your motivation high and your data accurate.
How Using a Notebook Can Help You Crush Debt
Debt feels overwhelming until you write it down. A dedicated notebook makes it concrete. Break your debt into chunks—credit card, student loans, car loans—and track every payment.
Imagine listing your debts: $3,000 on credit cards, $10,000 on student loans. You set a target—pay off $200 each month—and see your progress visually. That motivation is real.
According to financial experts, people who actively monitor their debt with written plans are 25% more likely to pay it off faster. The act of recording keeps your eyes on the prize.
Your Custom Blueprint: Making Your Notebook Fit Your Goals
Every financial journey is unique. Your notebook should reflect that. Want to save for a wedding? Track deposit deadlines, vendor payments, and gift budgets. Trying to get out of debt? Break down payments and stress points.
Start by identifying your top priorities. Then, create sections or pages tailored to those goals. Use color codes—green for savings, red for debts—to make it visual. Add motivational quotes or stickers to keep spirits high.
For example, Lisa, who’s saving for a house, keeps a dedicated page with her target savings, monthly check-ins, and a list of upcoming expenses—making her progress tangible and motivating.
Frequently Asked Questions
What should I include in my financial planning notebook?
Include sections for income, expenses, savings, debts, and financial goals. Add notes, reminders, and reflections to personalize your plan. The key is to make it comprehensive yet simple enough to keep up with daily.
Are digital or physical notebooks better for financial tracking?
It depends on your style. Digital notebooks sync easily, automate calculations, and update in real-time. Physical notebooks offer tactile satisfaction and less distraction. Combining both can give you flexibility and motivation.
How often should I update my financial planning notebook?
Make it a daily or weekly habit. Even 5 minutes a day or a quick review every Sunday can keep your goals front and center, reinforcing positive habits and catching mistakes early.
Can a financial notebook help me get out of debt?
Absolutely. Breaking debt into manageable chunks and tracking each payment turns a mountain into steps. Seeing your progress visually fuels motivation and keeps you accountable.
What are some recommended templates or products?
Popular options include printable PDFs like ‘The Budget Planner’ or apps like YNAB and EveryDollar. Many free templates are available online, customizable to fit your goals and style.
Conclusion
Your financial notebook is more than just a place to jot numbers—it’s a mirror reflecting your habits and a map guiding your goals. When you make it personal, consistent, and visually engaging, it transforms from a chore into a powerful motivator.
Pick the style that excites you, fill it with honest entries, and watch your financial confidence grow. In the end, it’s not just a notebook—it’s your secret weapon for money mastery.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.