Finding the right financial planning software depends heavily on what part of your financial life you’re trying to manage, because the options in this category solve very different problems. For overall money management, Quicken Classic Deluxe stands out with its broad toolkit for budgeting, bill tracking, and investment monitoring in one subscription. If you hate recurring fees, SavePoint Personal Finance Software is the strongest alternative, offering FIRE planning and Monte Carlo simulations on a one-time purchase that runs offline. For estate documents, Quicken WillMaker & Trust 2026 handles wills and trusts at a fraction of what an attorney charges. The main tradeoff you’ll face is between subscription-based tools with constant updates and one-time purchases you own outright — plus the fact that several items in this category are books and courses, not software at all. Keep reading for the full breakdown of which option fits your situation.

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
Key Takeaways
- Only six of the ten products in this category are actual software — four are books and guides, which matters if you came here expecting a tool rather than reading material.
- Quicken Classic Deluxe ranked highest for all-around planning because it covers budgeting, investments, and cash flow together, while most rivals specialize in just one area.
- SavePoint is the only option with Monte Carlo simulations and FIRE planning on a one-time purchase with no subscription, making it the value leader for long-horizon planners.
- The Quicken WillMaker & Trust editions overlap heavily; the deciding factor between them is delivery format (PC download versus PC/Mac and online access).
- Dave Ramsey-branded software appears twice in the lineup, and both versions prioritize debt payoff and budgeting over retirement modeling or investment analysis.



| financial planning software | Format |
|---|---|
| Quicken WillMaker & Trust 2026 | Download or Online Access |
| Financial Planning & Analysis | Print book |
| Dave Ramsey’s Personal Finance | — |
| Financial Planning and Analysi | Book |
| Quicken Classic Deluxe for New | Online Code |
| SavePoint Personal Finance Sof | — |
| Quicken WillMaker & Trust 2026 | — |
| Plan | Book |
| Financial Peace Personal Finan | Software |
| Financial Freedom Made Easy: S | Book |
More Details on Our Top Picks
Quicken WillMaker & Trust 2026 – Estate Planning Software – PC Download & Online
Quicken WillMaker & Trust 2026 earns its spot as the estate-planning anchor of this roundup. While most options here focus on budgeting or corporate analysis, this one tackles the documents that protect your family after you’re gone: wills, living trusts, powers of attorney, and health care directives. The step-by-step interview format translates dense legal language into plain questions, which makes it a realistic alternative to a four-figure attorney bill for straightforward estates. Compared with Quicken Classic Deluxe, which tracks day-to-day accounts, WillMaker is purely about legacy documents — the two serve different jobs entirely. The tradeoff is real, though: it isn’t a substitute for legal advice on complicated estates, and laws change, so documents may need updating.
Pros:- Step-by-step interview format makes legal documents approachable
- Covers a wide range of documents: will, living trust, directive, power of attorney, transfer on death deed
- Works on both Windows and Mac via download or online access
- Far more affordable than hiring an attorney for basic documents
Cons:- Not a replacement for professional legal advice on complex situations
- Legal requirements change, so documents may need periodic review and software updates
Best for: Individuals and couples with straightforward estates who need valid wills and directives without attorney fees
Not ideal for: Anyone with a complex estate, business ownership, or blended-family disputes — a lawyer is the safer route
- Platform:PC, Online
- Type:Estate Planning Software
- Documents Included:Will, Living Trust, Health Care Directive, Power of Attorney
- Additional Documents:Transfer on Death Deed
- Format:Download or Online Access
- Operating Systems:Windows, Mac
- Model Year:2026
Our verdict“If your goal is protecting your family’s future with valid estate documents at low cost, this is the clear pick over generic budgeting tools.”
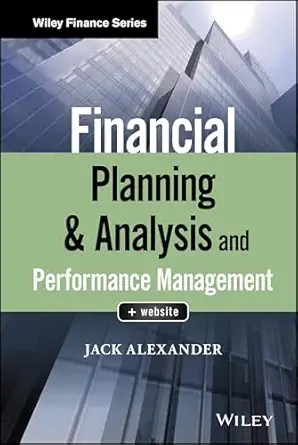
Financial Planning & Analysis and Performance Management (Wiley Finance)
Financial Planning & Analysis and Performance Management from Wiley Finance is the professional-grade reference in this lineup. Where Dave Ramsey’s Personal Finance Software targets household budgeting, this book targets the people who build budgets, forecasts, and performance frameworks for entire organizations. Its in-depth analytical techniques and practical strategies make it a strong companion for FP&A analysts, controllers, and MBA students preparing for careers in corporate finance. The breadth is genuinely useful — it connects planning to performance measurement rather than treating them as separate disciplines. The tradeoff is density: readers without a grounding in accounting or finance may find it heavy going, and unlike software options here, it delivers knowledge rather than automation.
Pros:- Rigorous, in-depth coverage of financial planning and analysis techniques
- Connects planning directly to performance management frameworks
- Includes practical examples and real strategies, not just theory
- Credible Wiley Finance pedigree for professional development
Cons:- No accompanying software, templates, or digital resources mentioned
- Too technical for readers without a finance or accounting background
Best for: FP&A analysts, controllers, and finance students who need a rigorous professional reference
Not ideal for: Beginners or casual readers — the technical depth assumes existing finance knowledge
- Format:Print book
- Publisher:Wiley (Wiley Finance series)
- Category:Financial Planning and Analysis / Performance Management
- Audience:Finance professionals, students
- Content Type:Techniques, practical examples, strategies
- Difficulty Level:Intermediate to advanced
Our verdict“This is the choice when you need corporate-level FP&A depth rather than personal money management tools.”
Dave Ramsey’s Personal Finance Software Version 5.3
Dave Ramsey’s Personal Finance Software Version 5.3 occupies the beginner-friendly, debt-payoff corner of this roundup. It’s built around the Ramsey philosophy of taking control of your money quickly, with a user-friendly interface that skips the steep learning curve of something like Quicken Classic Deluxe, which packs in investment and property tracking that many first-time budgeters don’t need yet. If your priority is getting a budget running tonight rather than managing a full portfolio, this simpler tool makes sense. The tradeoff cuts both ways: sparse documentation and limited feature detail mean buyers are trusting the Ramsey methodology more than the software itself. Compared with SavePoint, which offers advanced Monte Carlo simulations, this is deliberately basic — that’s the point.
Pros:- Very easy interface for users new to budgeting software
- Built around a proven debt-elimination methodology
- Gets a working budget up and running quickly
- Well suited to Ramsey followers already following the baby steps
Cons:- Limited published detail on features and capabilities
- Lacks advanced planning tools like forecasting or simulations
Best for: Debt-focused beginners who want a simple, philosophy-driven budgeting tool
Not ideal for: Data-hungry planners who want simulations, forecasting, or granular account tracking
- Version:5.3
- Category:Personal Finance / Budgeting Software
- Core Function:Budgeting and money management
- Approach:Dave Ramsey debt-elimination methodology
- Ease of Use:Beginner-oriented
- Planning Depth:Basic budgeting only
Our verdict“Choose this if you want simple, motivational budgeting; skip it if you expect analytical depth.”
Financial Planning and Analysis: Mastering Financial Planning and Analysis to Drive Smarter Business Decisions
Financial Planning and Analysis: Mastering FP&A to Drive Smarter Business Decisions is the more accessible of the two FP&A books in this roundup. Compared with the Wiley Finance title, which leans academic and reference-heavy, this one is oriented around practical business decision-making, making it a better fit for managers and small-business owners who want planning frameworks they can apply immediately rather than study. Its focus on best practices for effective financial management bridges the gap between raw data and decisions — a useful outcome for readers who aren’t career analysts. The tradeoff: it lacks detailed case studies, so readers who learn from worked real-world examples may find the guidance abstract, and beginners will still hit technical passages.
Pros:- Focused on applying analysis to real business decisions
- More approachable than heavyweight professional references
- Covers practical strategies and best practices, not just theory
- Suits both working professionals and students building business acumen
Cons:- Lacks detailed case studies to anchor the concepts
- Still too technical for complete beginners
Best for: Managers and small-business owners who want actionable FP&A frameworks without academic depth
Not ideal for: Learners who need step-by-step case studies or have zero finance background
- Format:Book
- Category:Financial Planning and Analysis
- Focus:Business decision-making
- Audience:Finance professionals, managers, students
- Content Type:Strategies and best practices
- Difficulty Level:Intermediate
Our verdict“If you make business decisions and want FP&A explained practically, this beats the denser Wiley title; theory-first readers should look there instead.”
Quicken Classic Deluxe for New Subscribers | 1 Year [PC/Mac Online Code]
” image=”https://m.media-amazon.com/images/I/61ypcFpjCuL._AC_SY445_SX342_QL70_FMwebp_.jpg” link=”0″]Best for All-in-One Money Management
View Latest PriceQuicken Classic Deluxe is the workhorse of this roundup — the option that pulls banking, credit cards, debt, investments, and property into a single dashboard. Unlike Dave Ramsey’s software, which stays deliberately simple, Deluxe goes wide: it tracks multiple accounts, builds budgets automatically from imported transactions, and projects debt-payoff scenarios so you can model tradeoffs before committing. The 30-day risk-free trial lowers the stakes for new subscribers, which matters given the learning curve. The tradeoff is the subscription model — after year one, you’re paying again to keep access, and the breadth that makes it powerful can overwhelm first-time users who just want a budget. For holistic planners, though, that breadth is the whole value proposition.
Pros:- Aggregates banking, credit cards, debt, investments, and property in one place
- Debt scenario projections help model payoff strategies
- Automatic budgets built from imported transactions
- 30-day risk-free trial for new subscribers
Cons:- Subscription renewal required every year to keep access
- Feature breadth creates a learning curve for new users
Best for: Households that want one tool to track accounts, investments, debt, and budgets together
Not ideal for: Budgeters who want a one-time purchase or only need basic expense tracking
- Platform:PC / Mac
- Duration:1 Year subscription
- Format:Online Code
- Account Types Supported:Bank, credit card, debt, investments, property
- Key Features:Budgeting, spending tracking, debt projections
- Trial:30-day risk-free trial for new subscribers
- Subscriber Type:New subscribers
Our verdict“This is the pick for whole-picture money management — just go in knowing it’s a recurring subscription, not a one-time buy.”
SavePoint Personal Finance Software – Budgeting, FIRE Planning, Monte Carlo Simulations, Balance Sheets, Cash Flow, Offline, No Subscriptions + 8GB USB Drive
SavePoint stands out as the most analytically ambitious option in this lineup. Where Quicken Classic Deluxe focuses on everyday budgeting and account aggregation, SavePoint pushes into serious long-range territory with Monte Carlo simulations and dedicated FIRE planning tools — the kind of probability-based forecasting usually reserved for advisor-grade platforms. The offline architecture is a genuine differentiator for buyers who keep sensitive net-worth data off the cloud, and the lifetime license avoids the subscription treadmill that Quicken Classic Deluxe locks you into. The tradeoff is real, though: there is no mobile app, so anyone who manages money primarily from a phone will feel constrained, and the depth of the planning modules assumes you already understand concepts like safe withdrawal rates. Compared with the beginner-oriented books in this roundup, this is software for planners, not learners.
Pros:- Monte Carlo simulations enable genuine scenario testing rather than simple projections
- Offline design keeps sensitive financial data off the cloud
- Lifetime license with no recurring subscription costs
- Supports 8 languages and 150+ currencies for international households
Cons:- Desktop-only — no mobile app for on-the-go budget tracking
- Steep learning curve for users new to formal planning tools
Best for: FIRE movement followers and serious DIY planners who want probability-based retirement modeling on their own machine
Not ideal for: Beginners who need hand-holding or anyone who wants mobile access — the desktop-only design and advanced modules assume financial fluency
- Offline Operation:Yes
- License Type:Lifetime, no subscription
- Device Compatibility:Windows PC and Mac
- Included Storage:8GB USB drive
- Languages Supported:8
- Currencies Supported:150+
- Core Modules:Budgeting, FIRE planning, Monte Carlo simulations, balance sheets, cash flow
Our verdict“This pick makes the most sense for financially literate FIRE planners who want advisor-style simulations without subscriptions or cloud storage.”
Quicken WillMaker & Trust 2026 – Estate Planning Software for PC/Mac & Online
Most titles in this roundup help you build wealth — WillMaker & Trust 2026 exists to protect what you have already built. Its guided interview format walks you through wills, trusts, powers of attorney, and health care directives one question at a time, producing documents tailored to your state’s requirements. That guided approach mirrors what makes Quicken Classic Deluxe approachable for budgeting, but applied to estate law instead of cash flow. The flexible delivery options — CD, download, or browser access — mean it works whether you are on an older machine or a newer laptop without a disc drive. The honest limitation: this is document creation, not legal counsel. Where SavePoint handles the accumulation phase of planning, WillMaker covers the distribution phase, and complex estates with business interests or multi-state property still warrant a lawyer.
Pros:- Step-by-step guided interview makes estate documents approachable for non-lawyers
- Produces state-specific, legally binding documents
- Covers wills, trusts, powers of attorney, and health care directives in one package
- Multiple delivery methods suit both older and modern computers
Cons:- Not a substitute for an attorney on complicated estates
- Limited to document creation — no ongoing financial planning or budgeting features
Best for: Individuals and families with straightforward estates who want legally valid documents without attorney fees
Not ideal for: Those with complex estates — blended families, business ownership, or significant trusts — who need personalized legal advice this software cannot provide
- Version:2026
- Platform:PC and Mac
- System Requirements:Windows 10/11, macOS 10.14 or higher
- Delivery Method:CD, download, or online access
- Document Types:Wills, trusts, powers of attorney, health care directives
- Guidance Format:Step-by-step guided interview
Our verdict“This is the right pick if your planning gap is legal protection rather than money management, and your estate is simple enough to document without counsel.”
Plan, Protect, Prosper: A Practical Guide to Retirement Income Planning, Wealth Management & Financial Security
Plan, Protect, Prosper takes the opposite approach to SavePoint: instead of running your numbers through simulations, it teaches you the framework behind sound retirement income decisions. That makes it a companion rather than a competitor to the software picks — you read this to understand decumulation strategy, then use a tool to model it. Compared with Financial Freedom Made Easy, which targets beginners digging out of debt, this book sits further along the journey, addressing readers who already have assets and are deciding how to draw them down. The wealth management coverage spans investment strategy and financial security in a single narrative, which helps readers see how the pieces connect. The drawback is the flip side of breadth: a book cannot recalculate your plan when markets move, and the lack of edition or author detail makes it harder to gauge depth before buying.
Pros:- Explains the reasoning behind retirement income strategies, not just the mechanics
- Connects wealth management and financial security topics into one framework
- Accessible entry point before investing in dedicated planning software
Cons:- No interactive tools — cannot personalize projections to your actual finances
- Limited publisher detail makes content depth and author credentials hard to verify
Best for: Pre-retirees and recent retirees who want to understand income strategy concepts before committing to planning software
Not ideal for: Readers who need interactive calculations — a static book cannot model your specific numbers the way SavePoint’s Monte Carlo tools can
- Format:Book
- Primary Focus:Retirement income planning
- Secondary Topics:Wealth management, financial security
- Audience Level:Pre-retiree to retiree
- Approach:Practical strategy guide
- Interactive Tools:None
Our verdict“A sensible starting point for readers in the wealth-preservation stage who want conceptual grounding before using planning tools.”
Financial Peace Personal Finance Software
Financial Peace occupies the simplest rung of this lineup: basic budgeting and money-management tools designed to change habits rather than model decades of future scenarios. Where SavePoint offers Monte Carlo simulations and balance sheets, this software keeps the focus on the fundamentals — tracking spending, building a workable budget, and developing discipline. That simplicity is its strongest asset for the right buyer, particularly someone following a debt-avoidance philosophy who finds full-featured planners like Quicken Classic Deluxe overwhelming. The honest comparison, though, is that this is a narrow tool in a roundup full of broader ones. It will not run retirement projections, generate estate documents like WillMaker, or teach strategy the way Plan, Protect, Prosper does. Sparse publicly available detail on features also means you are buying on philosophy rather than on a documented capability list, which is a real risk for comparison shoppers.
Pros:- Beginner-friendly interface that avoids overwhelming first-time budgeters
- Habit-focused approach helps build lasting money discipline
- Keeps the scope tight so daily use stays simple
Cons:- No advanced planning features such as retirement projections or net-worth tracking
- Limited publicly documented feature set makes it hard to compare against modern alternatives
Best for: Budget-first users who want a simple, habit-building tool aligned with debt-free living principles
Not ideal for: Planners who need forecasting, investment tracking, or retirement modeling — this stays firmly at the budgeting level
- Format:Software
- Primary Focus:Budgeting and money management
- Planning Features:Basic
- Retirement Tools:Not included
- Approach:Habit-building, debt-avoidance philosophy
- Audience Level:Beginner
Our verdict“Choose this only if straightforward budget discipline is your entire goal; anyone with longer-term planning needs should step up to SavePoint or Quicken.”
Financial Freedom Made Easy: Step-by-Step Guide to Eliminate Debt, Create a Financial Plan and Provide Security for You and Your Family
Of the two books in this roundup, Financial Freedom Made Easy targets the earlier stage of the journey. Its step-by-step structure walks beginners from debt elimination through building a first financial plan, whereas Plan, Protect, Prosper assumes you already have wealth to manage. That sequencing matters: readers drowning in credit card debt do not need Monte Carlo simulations — they need an ordered, actionable path, which is exactly what this book promises. Its family-security framing also distinguishes it from the software picks, since tools like Financial Peace manage the numbers while this explains the mindset and sequence behind them. The limitations are the mirror image of a book’s strengths: no worksheets respond to your inputs, nothing recalculates as circumstances change, and the absence of author credentials makes it hard to judge whether the advice rises above generic. Pair it with a budgeting tool rather than treating it as a complete system.
Pros:- Actionable, sequenced steps suit readers with no financial background
- Debt elimination is addressed before investing, matching the right order for beginners
- Family-security focus makes it relatable for household money decisions
Cons:- No interactive tools — cannot adapt to your actual numbers or changing circumstances
- Unverified author credentials and sparse detail make depth difficult to assess
Best for: Debt-burdened beginners who need a structured, jargon-free starting plan before using any software
Not ideal for: Readers past the debt stage — it offers little for those needing investment strategy or retirement income planning
- Format:Book
- Primary Focus:Debt elimination and financial planning basics
- Structure:Step-by-step guide
- Target Audience:Beginners and families
- Interactive Tools:None
- Coverage Area:Debt payoff, financial plan creation, family security
Our verdict“A reasonable first rung for families starting from debt, provided you treat it as a primer and add budgeting software alongside it.”
How We Picked
I evaluated each product through the lens of practical financial planning outcomes: can it help a real household build a budget, project retirement readiness, or produce legally usable documents? I weighed breadth of planning features (budgeting, cash flow, investments, estate documents), pricing model (subscription versus one-time purchase), platform flexibility, and how much financial knowledge the user needs on day one. Products that solve multiple planning needs in one place ranked higher than single-purpose tools.
Ranking also reflected who each product is actually for. Books and guides weren’t dismissed — they serve self-educators well — but they were placed lower for readers searching for working software. Subscription tools earned credit for continuous updates and bank connectivity, while offline one-time purchases earned credit for data privacy and long-run savings. The ordering favors options with the clearest fit between their feature set and a specific buyer’s situation.
| financial planning software | Format |
|---|---|
| Quicken WillMaker & Trust 2026 | Download or Online Access |
| Financial Planning & Analysis | Print book |
| Dave Ramsey’s Personal Finance | — |
| Financial Planning and Analysi | Book |
| Quicken Classic Deluxe for New | Online Code |
| SavePoint Personal Finance Sof | — |
| Quicken WillMaker & Trust 2026 | — |
| Plan | Book |
| Financial Peace Personal Finan | Software |
| Financial Freedom Made Easy: S | Book |
Factors to Consider When Choosing Financial Planning Software
Choosing financial planning software is less about finding the most powerful product and more about matching the tool to the specific job — and avoiding a few common mistakes that buyers make in this category.
Software Versus Educational Content
The single biggest mistake buyers make in this category is assuming every product labeled “financial planning” is software. Several top-selling items are actually books and self-study guides that teach planning concepts rather than automate them. If you want bank feeds, dashboards, and projections, verify you’re buying an application, not a paperback. That said, a good book paired with simple software can outperform expensive all-in-one tools for people who need to understand the reasoning behind their plan, not just see the numbers. Decide upfront whether your gap is knowledge or automation, because that answer eliminates half the lineup immediately.
Subscription Versus One-Time Purchase
Pricing models diverge sharply here, and the right choice depends on how long you’ll use the tool. Subscriptions like Quicken Classic Deluxe typically include ongoing updates, support, and connectivity that keeps working as banks change their systems. One-time purchases like SavePoint cost more upfront but never bill you again, and offline operation means your financial data never leaves your machine. A useful rule of thumb: if you expect to use the software daily for years, a subscription’s ongoing maintenance usually pays for itself. If you check in monthly or value privacy above convenience, a perpetual license is the better economic bet.
Planning Depth: Budgeting Versus Modeling
Most people searching for “financial planning software” actually need more than the budgeting tools they end up buying. Basic budgeting apps track what already happened; true planning tools model what could happen — retirement projections, Monte Carlo simulations, scenario testing. If your goal is early retirement or FIRE, Monte Carlo analysis matters because it shows the probability your plan survives bad market sequences, not just average returns. Buyers who skip this distinction often end up with a budget tracker and still no idea whether they’re on track. Match the tool’s analytical depth to the questions keeping you up at night.
Estate Planning Is a Separate Job
Wills, trusts, and healthcare directives are frequently bundled into the same shopping search as budgeting software, but they’re a different purchase with different standards. Estate planning software like WillMaker is excellent for straightforward situations — a simple will, naming guardians, basic powers of attorney. It is not a substitute for an attorney when you have blended families, business ownership, or sizable taxable estates. A common mistake is treating estate documents as a one-and-done task; they need revisiting after marriages, births, and major asset changes. Budget for periodic reviews even if the software itself is inexpensive.
Data Privacy and Connectivity Tradeoffs
Every cloud-connected planning tool trades convenience for exposure: linking accounts means your credentials and transaction data live somewhere outside your control. Offline tools eliminate that risk but require manual entry or file imports, which is the reason many people abandon them within months. Be honest about your tolerance for manual data entry before choosing the privacy-first option. The practical middle ground is using connected software with read-only access and strong account security, then exporting your data periodically. Whatever you choose, the best plan is the one you’ll actually keep updated.
Ease of Learning and Beginner Fit
Feature-rich planning software can be genuinely intimidating, and abandoned software helps nobody. Guided, debt-focused tools work well for beginners because they impose structure: you follow steps rather than build a plan from a blank page. Advanced users find that same structure restrictive. Before buying, consider whether the product offers sample plans, walkthroughs, or templates — the presence of these usually signals a gentler learning curve. A simpler tool you use consistently will beat a powerful one you open twice.
Frequently Asked Questions
Is Quicken Classic Deluxe worth the subscription compared to free budgeting apps?
It depends on whether you need planning depth beyond basic budgeting. Free apps generally handle expense tracking well, but Quicken Classic Deluxe adds investment monitoring, cash flow projection, and account consolidation that free tools typically cap or omit. The subscription also covers continuous updates, which matters because bank connectivity breaks without ongoing maintenance. If your financial life is simple — one checking account, no investments — the subscription is probably overkill. Households juggling multiple accounts, loans, and retirement balances usually find the consolidation alone justifies the annual cost.
What’s the difference between the two Quicken WillMaker & Trust 2026 versions?
The functional estate planning documents are essentially the same; the difference is delivery format and platform coverage. One version is a PC download with online access, while the other covers both PC and Mac with combined desktop and online use. If your household has mixed operating systems or you want to access your documents from the browser on any machine, the PC/Mac and online edition fits better. Pure Windows users can save a little with the download version and lose nothing meaningful. Neither version replaces legal advice for complicated estates, so the choice should hinge on your devices, not on document quality.
Do I really need Monte Carlo simulations in my financial planning?
If retirement timing is a core part of your plan, yes — and it’s the standout feature of SavePoint in this lineup. Averages hide risk: a plan that works “on average” can still fail if poor market returns hit early in retirement, a problem called sequence-of-returns risk. Monte Carlo simulation runs thousands of market scenarios and tells you the probability your plan survives, which is far more useful than a single straight-line projection. For people pursuing FIRE or retiring before traditional pensions and Social Security kick in, this analysis often changes withdrawal decisions. If you’re still in the debt-payoff stage, it’s a feature you can defer.
Are the books in this category a waste of money if I want software?
Not necessarily, and dismissing them entirely is a mistake some buyers regret. Books on financial planning and analysis teach the judgment that software can’t — how to interpret a Monte Carlo result, when to adjust a plan, what a withdrawal rate means for your lifespan risk. Many people buy powerful software and then don’t understand what the outputs are telling them, which is exactly the gap a good guide fills. The smarter approach is pairing a modest tool with a solid educational resource rather than paying for analytics you can’t act on. That said, if you only want automation, skip the books and put the budget toward software.
Which option is best if I’m drowning in debt rather than building wealth?
Start with the Dave Ramsey-style, debt-focused software in this lineup rather than general planning suites. Debt-heavy situations need behavioral structure — a defined payoff order, visible progress, and guardrails against new borrowing — more than they need retirement modeling. General tools like Quicken will show you the debt but don’t prioritize the psychology of eliminating it. Once high-interest debt is cleared, that’s the right moment to graduate to a tool with projections and investment tracking. Buying advanced planning software before fixing cash flow usually results in an expensive app you abandon.
Conclusion
The right pick here depends entirely on where you are in your financial journey. For best overall, Quicken Classic Deluxe earns the top spot with the widest coverage of budgeting, investments, and cash flow in one subscription. For best value, SavePoint is hard to beat — Monte Carlo simulations, FIRE planning, and balance sheets on a one-time purchase with no recurring fees. Beginners and anyone focused on escaping debt should start with Dave Ramsey’s Personal Finance Software or Financial Peace, both built around step-by-step guidance rather than blank-page planning. For a specific estate planning need, Quicken WillMaker & Trust 2026 delivers legally usable documents cheaply — just pick the edition matching your operating system. Finally, if your real gap is knowledge rather than tooling, the books in this lineup, especially the retirement income and FP&A guides, will do more for your plan than any dashboard. Buy for the problem you actually have today, and upgrade when your situation outgrows the tool.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.